ThriveAgric’s $3.93 Million Debt Bet Beats Equity Cash.
Most startup funding headlines chase the same story: how much equity a company sold and to whom. ThriveAgric’s latest raise breaks that pattern entirely. Instead of courting venture investors...
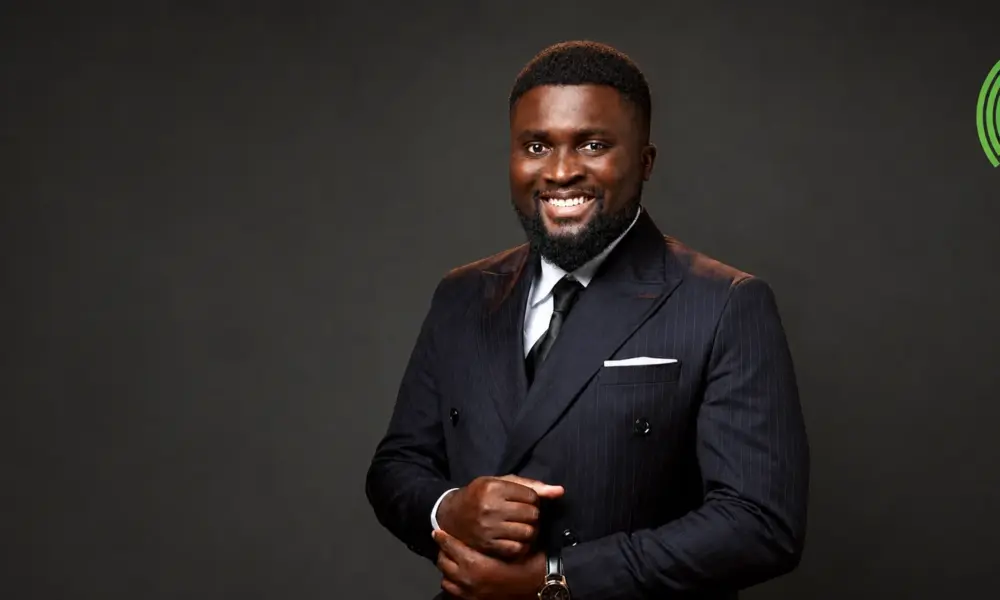
Most startup funding headlines chase the same story: how much equity a company sold and to whom. ThriveAgric’s latest raise breaks that pattern entirely. Instead of courting venture investors for another equity round, the Lagos-based, Y Combinator-backed agritech has turned to Nigeria’s debt capital markets, raising ₦5.3 billion (about $3.93 million) through its first-ever commercial paper issuance. The offer was oversubscribed, comfortably clearing its ₦5 billion target on strong institutional demand. It’s also just the opening move in a much bigger plan: a programme designed to eventually raise up to ₦50 billion (roughly $37.09 million). What makes this story worth a closer look isn’t the size of the raise; it’s the reasoning behind choosing debt at all, and what that choice reveals about how agritech businesses actually need to be financed.
Table Of Content
What ThriveAgric Raised and Why It Matters
ThriveAgric’s Series 1 commercial paper closed with demand well above its initial target, marking the company’s first entry into Nigeria’s formal debt markets. Until now, the company had leaned on bank lending and equity rounds to fund its operations. This shift opens an additional, more flexible channel for raising working capital, one that doesn’t require giving up further ownership of the business.
Chief executive Uka Eje framed the move as a governance milestone as much as a financial one, pointing to regulatory approval for the wider ₦50 billion programme as validation of the company’s financial discipline. For a company whose biggest historical obstacle has been accessing the right kind of capital, that validation carries weight beyond the naira figures involved.
Why Debt, Not Equity, Fits ThriveAgric’s Model
Matching Capital to the Cash Cycle
Startup financing conversations default to equity almost automatically, yet equity isn’t always the right tool. ThriveAgric’s core business, buying harvested produce from smallholder farmers, aggregating it, and reselling to processors and FMCG buyers, moves considerably faster than the agricultural production cycle itself, which can stretch nine to twelve months. Because the commercial paper is meant to fund that faster-turning trading cycle rather than the slower farming cycle, short-term debt is arguably a cleaner fit than long-term equity.
This distinction matters more than it might first appear. Financing structures that don’t match a business’s actual cash flow can quietly become a liability. Long-term equity used to cover short-term working capital needs tends to be expensive relative to the problem it solves, while short-term debt taken on without predictable repayment sources can create dangerous pressure instead of flexibility.
A Cheaper, More Sustainable Source of Capital
Eje has argued that agricultural financing becomes more scalable once it’s genuinely affordable, and that accessing the capital markets, rather than relying solely on banks, gives ThriveAgric a shot at exactly that kind of pricing. As he put it, the point of this raise is that it is debt to expand our business in Nigeria, not another equity sale. Broadening the lender base to include investment houses and asset managers, alongside traditional banks, could help keep that cost of capital moving in the right direction over future issuances.
From Smallholder Farmers to FMCG Buyers
ThriveAgric’s ambitions extend well past being a lender. The company has built what amounts to an aggregation engine: it finances farmers to grow crops, helps them repay through part of the harvest, then collects and resells the surplus to established buyers. That structure gives smallholder farmers something many of them lack, a reliable route to market, while giving ThriveAgric a steady pipeline of produce to sell onward.
Underpinning all of this is the company’s Agricultural Operating System, a data platform that tracks farmers through onboarding, input distribution, field monitoring and inventory management. Over time, that data trail could do more than run operations; it could become the foundation for helping smallholder farmers build credit histories strong enough to borrow directly from financial institutions, rather than through ThriveAgric alone.
Since its 2017 founding by Eje and Ayodeji Arikawe, the company has raised roughly $61.3 million in total funding and now works with more than 1.3 million smallholder farmers across 26 Nigerian states, supported by around 5,000 field agents. It has also expanded into Ghana, Kenya, Uganda and Rwanda, though Nigeria still accounts for the bulk of its business. This latest raise, notably, is aimed squarely at deepening that Nigerian core rather than funding further geographic growth.
The Bigger Test Is Still Ahead
A larger commercial paper programme brings larger expectations along with it. Scaling from ₦5.3 billion to a potential ₦50 billion means ThriveAgric will need to prove that additional debt actually converts into faster commodity turnover, dependable repayments, and durable growth, not just a bigger balance sheet.
That’s the real risk hiding behind any capital raise: assuming that cheaper, more available financing automatically fixes underlying business weaknesses. It doesn’t. Capital tends to amplify whatever model is already in place, for better or worse, rather than repair one that isn’t working.
The Takeaway for Founders
ThriveAgric’s approach offers a practical lesson that extends well beyond agritech: financing structure should follow the cash cycle, not startup convention. Businesses moving money quickly through short trading cycles may be better served by targeted debt than by equity raised for the wrong kind of problem. Whether ThriveAgric’s bet pays off will depend on execution over the next twelve months, but the underlying logic, matching capital type to how money actually moves through the business, is one every founder weighing similar choices would do well to consider.
Disclaimer
Africa Agricultural Network (AAN) is committed to informing and empowering agricultural communities across Africa as per our mandate. This article is intended for informational purposes only. Financial figures, quotes and business details referenced here are drawn from ThriveAgric’s public statements and reporting available at the time of writing, and terms of the commercial paper programme may change as further issuances proceed.



No Comment! Be the first one.